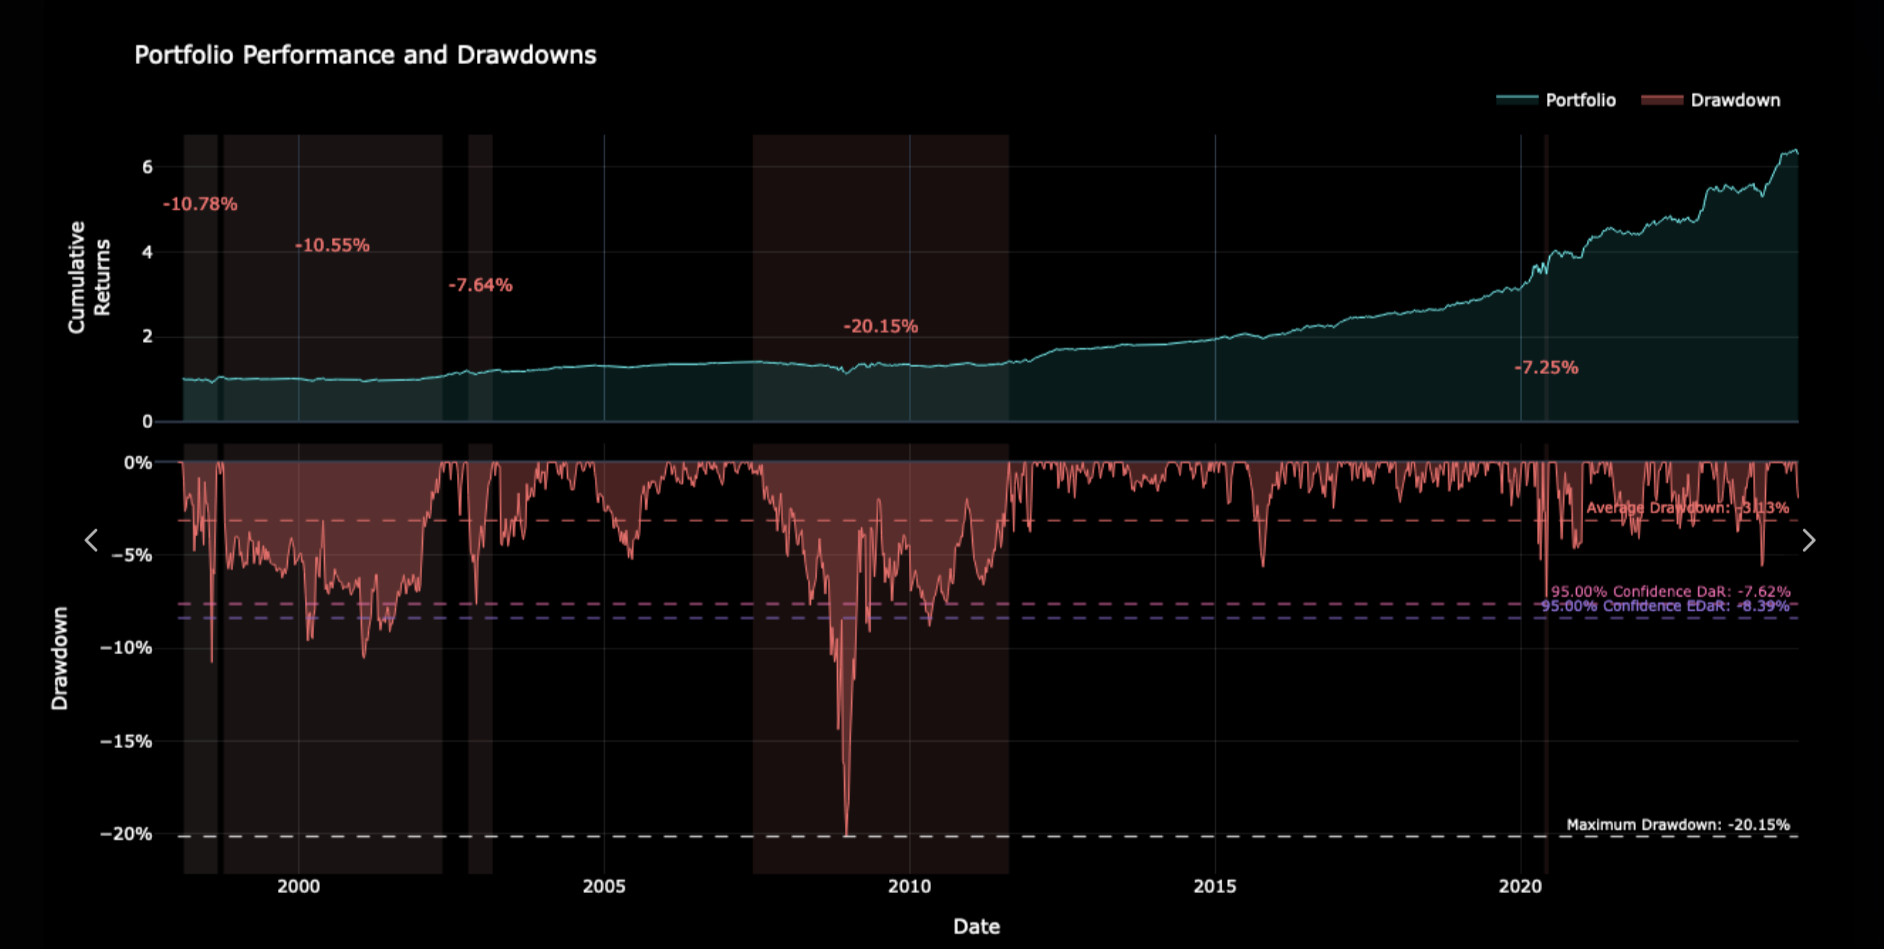
Drawdown and return
Portfolio performance tied to canonical NAV and return series — same book as the PM view.
Risk & performance
Risk only changes decisions when it is close to the investment workflow. OneBook connects exposures, drawdowns, attribution, factor views, scenarios, API/SDK/MCP access and Decision Packets to the portfolio state and warehouse facts that produced them.
Analytic surfaces
Portfolio performance tied to canonical NAV and return series — same book as the PM view.
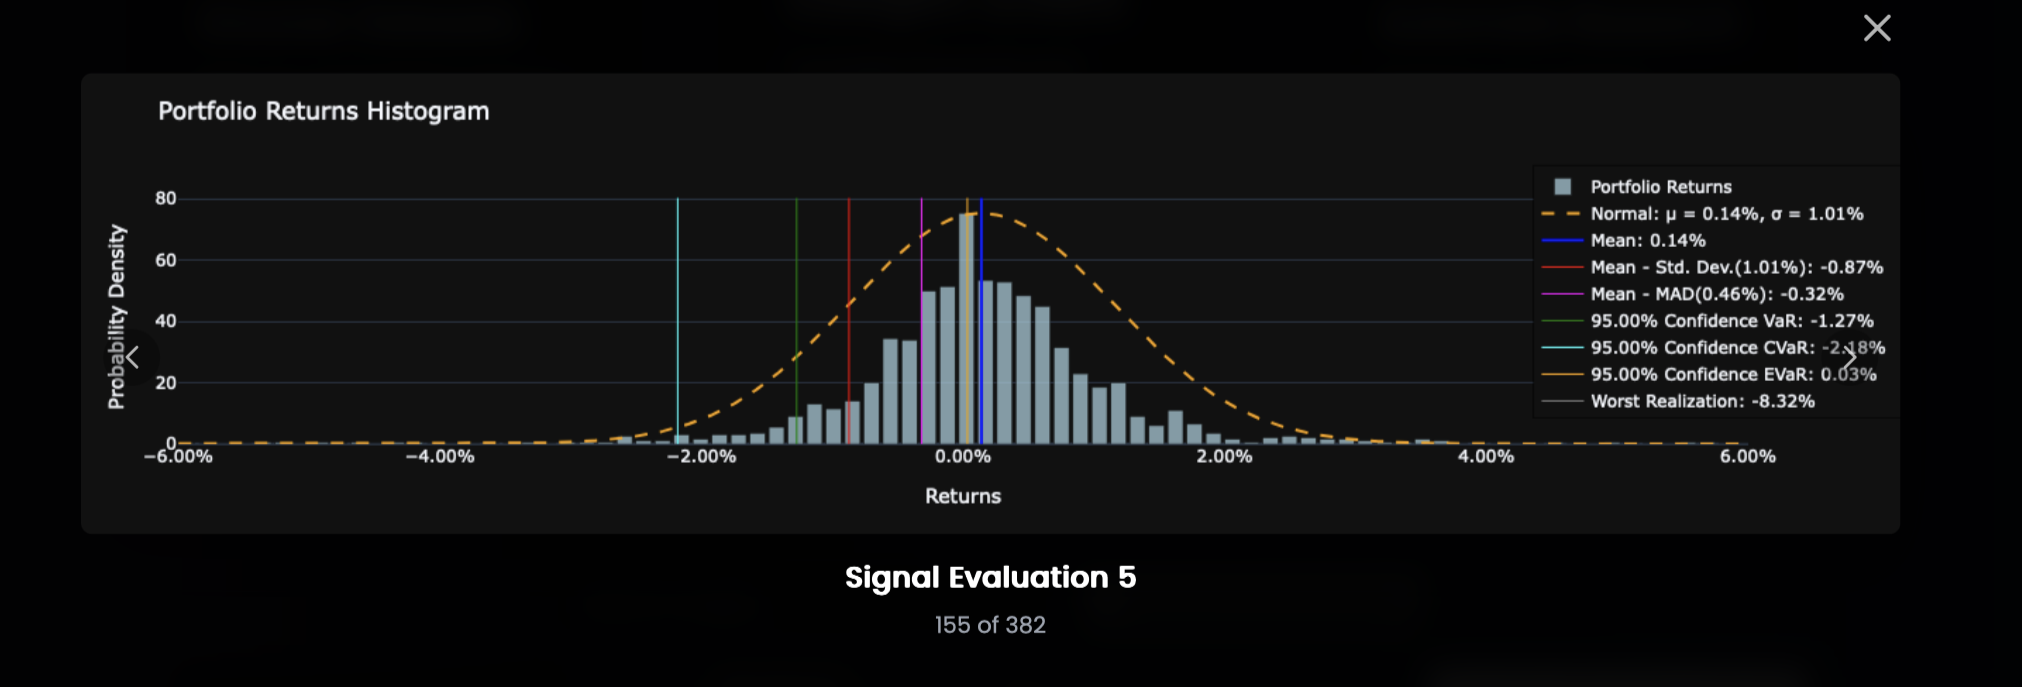
Exposure distribution, confidence bands and diagnostic surfaces for portfolio review.
Return drivers by segment, factor, benchmark or portfolio slice — traceable to input state.
Stress and what-if outputs connected to the portfolio state and data snapshot used.
Attach the risk context, model run and portfolio impact to the decision record the PM and CIO review.
Expose risk state through UI, API, SDK and MCP without bypassing permissions or losing audit evidence.
Available now
Technical preview and roadmap
Product proof
Next step
See how OneBook ties risk output to portfolio state, Decision Packets and governed API/SDK/MCP access.
Request Demo